Then, credit the income summary account with the total revenue amount from all revenue accounts. In summary, permanent accounts hold balances that persist from one period to another. In contrast, temporary accounts capture transactions and activities for a specific period and require resetting to zero with closing entries. Closing entries are a fundamental part of accounting, essential for resetting temporary accounts and ensuring accurate financial records for the next period.
Closing Entry: What It Is and How to Record One
Income summary is a holding account used to aggregate all income accounts except for dividend expenses. It’s not reported on any financial statements because it’s only used during the closing process and the account balance is zero at the end of the closing process. Temporary account balances can be shifted directly to the retained earnings account or an intermediate account known as the income summary account. The net income (NI) is moved into retained earnings on the balance sheet as part of the closing entry process.
- Closing entries, on the other hand, are entries that close temporary ledger accounts and transfer their balances to permanent accounts.
- That’s exactly what we will be answering in this guide – along with the basics of properly creating closing entries for your small business accounting.
- All of Paul’s revenue or income accounts are debited and credited to the income summary account.
- It is permanent because it is not closed at the end of each accounting period.
- The Printing Plusadjusted trial balance for January 31, 2019, is presented inFigure 5.4.
- The fourth entry requires Dividends to close to the RetainedEarnings account.
- These accounts were reset to zero at the end of the previous year to start afresh.
Step 3: Closing the income summary account
When making closing entries, https://www.bookstime.com/articles/freshbooks the revenue, expense, and dividend account balances are moved to the retained earnings permanent account. If you own a sole proprietorship, you have to close temporary accounts to the owner’s equity instead of retained earnings. There may be a scenario where a business’s revenues are greater than its expenses.
Step #1: Close Revenue Accounts
- We have completed the first two columns and now we have the final column which represents the closing (or archive) process.
- You can do this by debiting the income summary account and crediting your capital account in the amount of $250.
- In some cases, accounting software might automatically handle the transfer of balances to an income summary account, once the user closes the accounting period.
- They’d record declarations by debiting Dividends Payable and crediting Dividends.
We could do this, but by having the Income Summaryaccount, you get a balance for net income a second time. This givesyou the balance to compare to the income statement, and allows youto double check that all income statement accounts are closed andhave correct amounts. If you put the revenues and expenses directlyinto retained earnings, you will not see that check figure. Nomatter which way you choose to close, the same final balance is inretained earnings.
What is your current financial priority?
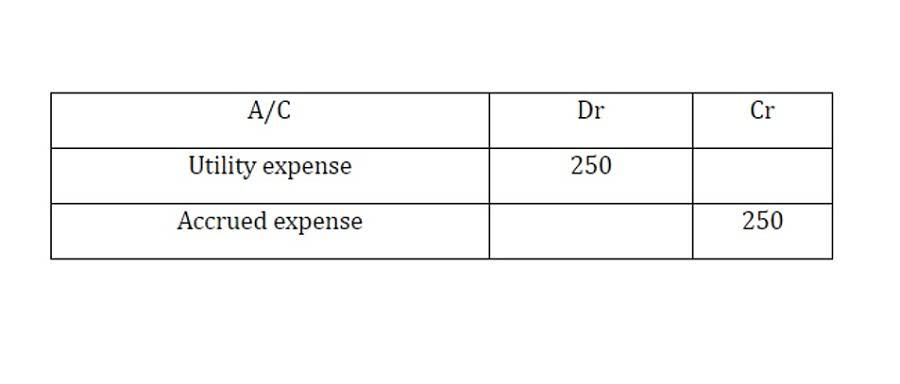
Closing entries are an important facet of keeping your business’s books and records in order. By maintaining your bookkeeping, you can ensure that you are constantly kept informed. As well as being consistently up-to-date on the financial health of your business. If your expenses for December had exceeded your revenue, you would have a net loss. When closing expenses, you should list them individually as they appear in the trial balance.
- They zero-out the balances of temporary accounts during the current period to come up with fresh slates for the transactions in the next period.
- The articles and research support materials available on this site are educational and are not intended to be investment or tax advice.
- Printing Plus has a $4,665 credit balance in its Income Summaryaccount before closing, so it will debit Income Summary and creditRetained Earnings.
- Organizations can achieve up to 95% journal posting automation with a pre-filled template, reducing errors and discrepancies and providing a reliable view of financial data.
- Revenue is one of the four accounts that needs to be closed to the income summary account.
For the past 52 years, Harold Averkamp (CPA, MBA) has worked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online. The articles and research support materials available on this site are educational and are not intended to be investment or tax advice. All such information is provided solely for convenience purposes only and all users thereof should be guided accordingly. For information pertaining to the registration status of 11 Financial, please contact the state securities regulators for those states in which 11 Financial maintains a registration filing. Then, just pick the specific date and year you want the closing process to take place, and you’re done!
Step 3: Close Income Summary account
The accounting assumption here is that any profit earned during the period needs to be retained for use in future company investments. Once we have made the adjusting entries for the entire accounting year, we have obtained the adjusted trial balance, which https://x.com/BooksTimeInc reflects an accurate and fair view of the bakery’s financial position. The trial balance is like a snapshot of your business’s financial health at a specific moment. It lists the current balances in all your general ledger accounts. In this case, we can see the snapshot of the opening trial balance below. Remember, dividends are a contra stockholders’ equity account.It is contra to retained earnings.
Printing Plus has a $4,665 credit balance in its Income Summaryaccount before closing, so it will debit Income Summary and creditRetained Earnings. However, if the company also wanted to keep year-to-dateinformation from month to month, a separate set of records could bekept as the company progresses through the remaining months in theyear. For our purposes, assume that we are closing the books at theend of each month unless otherwise noted. The Income Summary balance is ultimately closed to the capital account.
Well, dividends are not part of the income statement because they are closing entries not considered an operating expense. In other words, they represent the long-standing finances of your business. That’s exactly what we will be answering in this guide – along with the basics of properly creating closing entries for your small business accounting.